Key Points
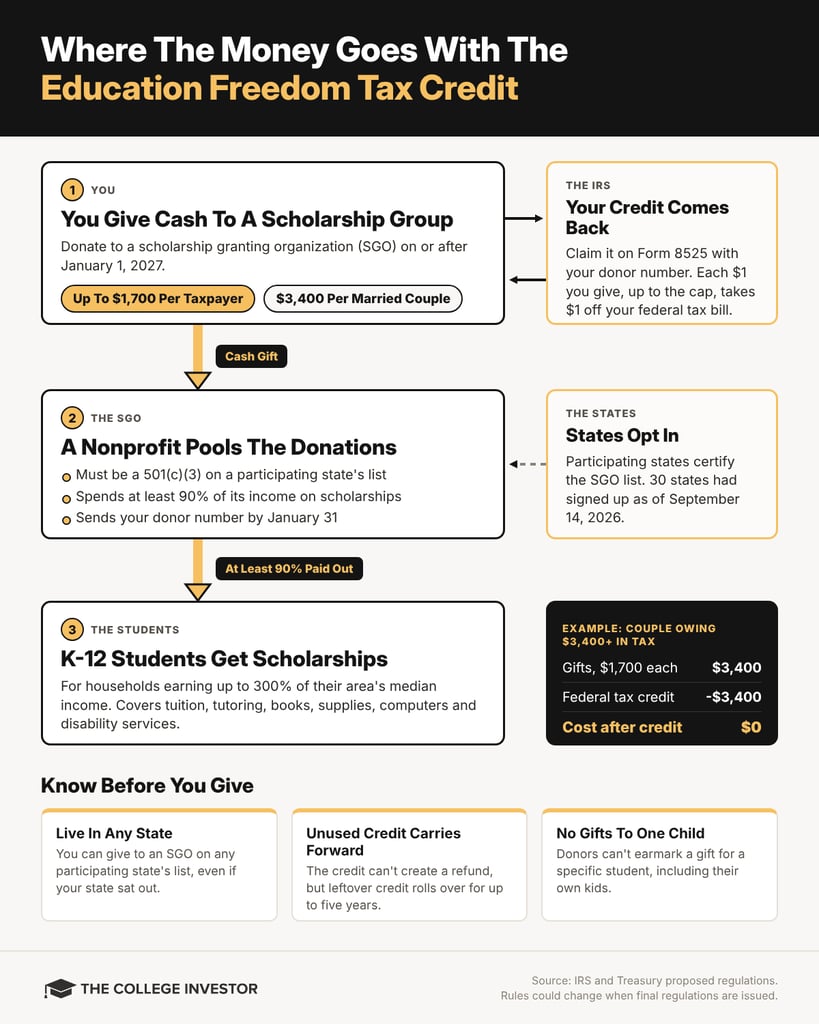
- Starting January 1, 2027, a cash gift to an approved scholarship granting organization earns a dollar-for-dollar federal tax credit of up to $1,700 per taxpayer, or $3,400 for a married couple when each spouse gives $1,700.
- You can donate from any state, but the organization must be on a participating state’s list. Thirty states had opted in as of September 14, 2026.
- The credit is nonrefundable, unused amounts carry forward five years, and you claim it on Form 8525 using a donor number the organization sends you.
Beginning January 1, 2027, the federal government will give taxpayers a full dollar back for every dollar they donate to a K-12 scholarship organization, up to $1,700 per person.
Congress created the Federal Scholarship Tax Credit in the One Big Beautiful Bill Act, and it’s often called the Education Freedom Tax Credit. Treasury and the IRS have released proposed regulations and temporary regulations that spell out how donors actually claim it.
The Education Freedom Tax Credit is a nonrefundable federal tax credit equal to the cash you give to an eligible scholarship granting organization (SGO), capped at $1,700 per taxpayer per year. A $1,000 gift cuts your federal tax bill by $1,000, and the benefit grows dollar for dollar until it hits the $1,700 cap.
That makes it far more valuable than a normal charitable gift. A tax credit beats a tax deduction because it comes straight off your bill. A $1,700 deduction saves a donor in the 22% bracket just $374, while a $1,700 credit saves the full $1,700.
How Does A Married Couple Reach $3,400?
A married couple filing jointly can claim up to $3,400, because the proposed rules apply the $1,700 limit to each individual taxpayer. Journal of Accountancy confirms the $3,400 joint figure from the Treasury guidance.
The catch is that each spouse’s credit is based on that spouse’s own contributions. The cleanest approach is for each spouse to give $1,700 in their own name and get their own donor number. One $3,400 gift from one spouse may only produce a $1,700 credit. With this credit, the paperwork matters as much as the credit-versus-deduction math.
What Does A Scholarship Gift Actually Cost You?
For most donors who owe at least $1,700 in federal income tax, a $1,700 gift costs nothing after the credit. The table below shows how the math changes when your tax bill is small, when a state credit also applies, or when you give more than the cap.
What A Scholarship Gift Costs After The Federal Credit In 2027
| Donor Scenario | Gift | Federal Credit | Cost After Credits |
|---|---|---|---|
| Single Filer, Owes At Least $1,700 | $1,700 | $1,700 | $0 |
| Married Couple, Each Spouse Gives $1,700 | $3,400 | $3,400 | $0 |
| Single Filer, Owes Only $1,000 | $1,700 | $1,000 now, $700 carried forward | $700 until used |
| State Credit Of $500 Also Applies | $2,500 | $1,700 | $300 |
| Single Filer Gives Above The Cap | $5,000 | $1,700 | $3,300, before any deduction |
Source: IRS and Treasury proposed regulations. The College Investor.
Three rules matter here:
- The credit is nonrefundable, so like most federal tax credits it can cut your tax to zero but won’t produce a refund, and any unused amount carries forward for up to five years.
- If your state offers its own scholarship credit, the proposed rules subtract the state credit from your gift before applying the $1,700 cap, which protects the full federal credit when you give a little more.
- Anything you give above the cap may still count as a regular charitable deduction if you itemize, but the credited portion can’t be deducted twice.
Can You Donate If Your State Didn’t Opt In?
Yes. The proposed rules let a taxpayer give to an eligible SGO “without regard to the taxpayer’s residence,” as long as that organization appears on a participating state’s list. A donor in California could claim the credit for a gift to an SGO certified by Texas. For donors, the list of participating states matters because it decides which SGOs qualify, not whether you can give.
The IRS lists 30 states that made an advance election for 2027 as of September 14, 2026. States have until January 1, 2027 to opt in and until February 15, 2027 to submit their SGO lists.
Governors in Hawaii, Minnesota, New Mexico, and Oregon have said their states won’t participate, according to States Newsroom.
Where Does Your Donation Go?
Your gift funds K-12 scholarships for students from households earning up to 300% of their area’s median income. AFC’s eligibility research found that nearly 92% of U.S. children fall under that limit.
Scholarships can cover private school tuition, tutoring, books, supplies, computers, and services for students with disabilities, including for kids who stay in public school. SGOs must be 501(c)(3) public charities, spend at least 90% of their income on scholarships, and serve at least 10 students who don’t all attend the same school. You can’t earmark a gift for a specific child, which means a family can’t use the credit to pay their own child’s private school tuition. A 529 plan is the better tool for that purpose.
How Do You Claim The Education Freedom Tax Credit?
You claim the credit on Form 8525, attached to your federal return, using the unique donor number your SGO provides. Only cash gifts made on or after January 1, 2027 count, so a donation in December 2026 won’t qualify for the Education Freedom Tax Credit.
The timeline for a 2027 gift works like this. Your SGO must send a written acknowledgment with your donor number by January 31, 2028. You then report that number on Form 8525 with your 2027 return, filed in early 2028. Leaving the donor number off creates a presumption that the credit is disallowed, so keep the acknowledgment with your tax records alongside your other supporting documents for that year’s return.